The 2026 Commercial Insurance Market: One Market, Two Directions
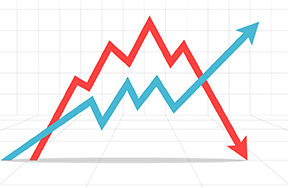
Commercial insurance buyers are navigating a market that seems to be moving in two directions at once. Property insurance is finally loosening, offering lower premiums and broader terms for well managed risks. At the same time, casualty lines — especially commercial auto, umbrella, and general liability — continue to tighten. It’s a split market, and understanding the divide is essential for planning renewals in 2026.
Property Finds Its Footing Again After nearly nine years of steady increases, property insurance is showing clear signs of softening. Carriers have more capacity, reinsurance costs have stabilized, and early year catastrophe losses have been manageable. Businesses with strong fire protection, updated electrical systems, and consistent maintenance are seeing meaningful improvements in pricing. Casualty Continues to Harden While property improves, casualty lines tell a different story. Commercial auto remains one of the most challenging lines, driven by rising repair costs, advanced vehicle technology, and distracted driving losses. Liability claims are also becoming more expensive, fueled by broader liability theories and larger jury awards. Why the Split Exists The divergence comes down to two forces moving in opposite directions. Property losses have stabilized, and carriers have better tools to evaluate risk. Liability losses, on the other hand, continue to grow. Medical inflation, litigation trends, and social inflation all push casualty claim costs higher, and carriers price accordingly. Navigating the Year Ahead In a split market, preparation matters more than ever. Businesses that document their safety programs, maintain their buildings, and update contracts and indemnification agreements will be better positioned. Early conversations with brokers can help avoid surprises, especially in casualty lines where increases may be unavoidable.
Key takeaways:
The relief, however, has boundaries. Secondary perils — wildfire, hail, inland flooding — still dominate global losses, and underwriters remain cautious. Properties in high risk zones continue to face higher deductibles, stricter terms, and closer scrutiny. The softening is real, but it’s selective.
Another factor shaping the property market is the growing reliance on technology. Carriers are using aerial imagery, remote sensors, and automated inspections to verify building conditions and maintenance practices. This gives them greater confidence in well managed risks and allows them to differentiate more sharply between properties with strong controls and those with deferred maintenance. In many cases, the quality of documentation and data a business can provide is becoming just as important as the physical condition of the building itself.
Umbrella carriers are responding by raising attachment points and tightening wording. Even well run businesses may see increases simply because the underlying cost of claims keeps rising. In some industries — transportation, construction, manufacturing — casualty underwriters are asking for more documentation, more detail, and more evidence of safety protocols before offering terms.
The result is a market where a business might see a welcome decrease in its property premium while facing a significant increase in auto or umbrella — all in the same renewal cycle.
This Just In ... Property Rates Finally Ease — But Not for Everyone
The 2026 Commercial Insurance Market: One Market, Two Directions
AI Risks Are Now Real Risks: What Businesses Need to Know
Tariffs, Trade Policy, and the Rising Cost of Claims
Workers’ Compensation: Stable, But Showing Early Warning Signs
The information presented and conclusions within are based upon our best judgment and analysis. It is not guaranteed information and does not necessarily reflect all available data. Web addresses are current at time of publication but subject to change. SmartsPro Marketing and The Insurance 411 do not engage in the solicitation, sale or management of securities or investments, nor does it make any recommendations on securities or investments. This material may not be quoted or reproduced in any form without publisher’s permission. All rights reserved. ©2025 The Smarts Publishing. Tel. 877-762-7877. www.smartspublishing.com